Introduction
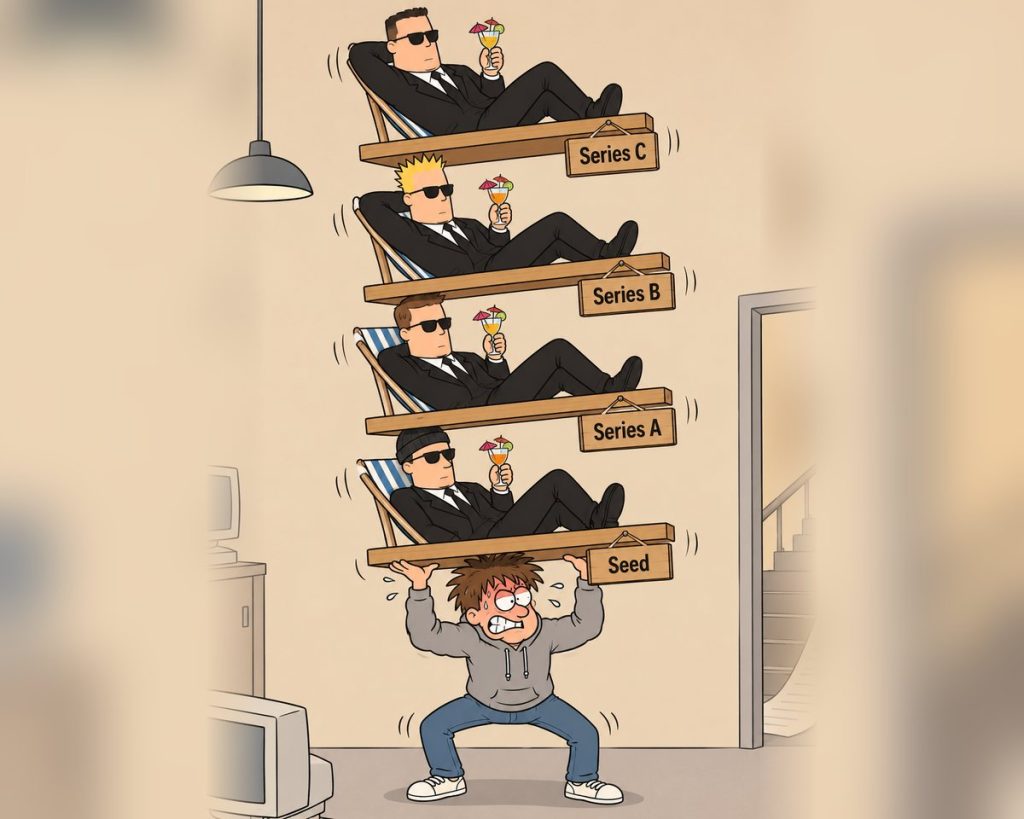
Structuring a financing round requires the right choice of financing instrument (e.g. convertible loan or equity), a targeted selection of the investor base and a legally sound design of governance and control rights. What is decided here has an effect beyond the upcoming round and forms the basis for all subsequent rounds. Given the many parameters and framework conditions to be taken into account, structuring can be compared to a game of Tetris.
Key Takeaways
- Convertible loans (CLAs) are best suited for fast, low-cost bridge financing without a valuation, whereas equity rounds typically send a stronger growth signal to the market.
- Selecting the right investor mix is like “VC Tetris”: investor type, ticket size, value-add and ability to follow on in later rounds must fit together – and the round must also think ahead to the next.
- Passive investors who add no real value should remain the exception; what is needed are “functional champions” or “application champions” with robust specialist or market expertise.
- Legally decisive are a precise conversion mechanism for convertible loans, a lean investor base capable of making decisions, and governance that does not block operational decisions.
- Every round should be designed to be compatible with the next – conflicting investor rights or unclear liquidation waterfalls come back to haunt you in the following round.
CLA vs. Equity Round – Decision Criteria
Convertible loan agreements and classic equity rounds differ in almost all relevant dimensions. A convertible loan scores on speed (often with existing investors), lower transaction costs and avoiding a company valuation – which may be risky in difficult market phases – but the cap table can become unwieldy with several successive CLAs. An equity round requires more time for structured negotiations and, as a rule, at least one new investor, but offers a clear, stable cap table and a strong positive growth signal to the market and enables a transparent company valuation – although investors typically demand more governance and control rights in return.
Selecting the Right Investors (“VC Tetris”)
Selecting the investor base can be compared to a dynamic game of Tetris: you never know in advance which investor will be available next, you never see all the pieces at once, and too strong a focus on the current round can block the next. Investor types differ considerably in ticket size and in their ability to follow on in future rounds – from business angels (€50,000 to €500,000, high risk appetite, active mentoring) through family offices and state-backed VCs to classic VCs, corporate VCs and late-stage investors (from €50 million upwards). A mix that includes both investors able to take up their pro rata in follow-on rounds and different investor types is advisable. As important as ticket size is the non-financial value-add: passive investors who contribute nothing except cash should remain the exception – instead, “functional champions” or “application champions” with robust specialist or industry expertise are sought. In later rounds, additional criteria such as the investors’ region of origin (e.g. for valuation or exit purposes) can become relevant.
Legal Pitfalls in Structuring
Four legal topics deserve particular attention when structuring a round:
- Equity vs. convertible loan: unclear conversion rules (timing, valuation, trigger events) and legally unworkable GmbH structures are the main danger – a remedy is a precise, legally sound conversion mechanism consistent with capital increase and notarial requirements.
- Composition of the investor base: many small investors with individual voting rights threaten to slow down or block decisions; bundling through pooling or nominee structures as well as a ‘lead’ investor create a cap table capable of acting.
- Governance via the advisory board: there is a risk of overly broad consent requirements that paralyse the management; the solution lies in narrowly drawn consent requirements for material matters and a clear separation of advisory and management roles.
- Every round should be checked for compatibility with the next round – conflicting investor rights or unclear liquidation waterfalls make later negotiations considerably harder.
Panel
Start-up Lounge Vol. 5 · Session held on 22 April 2026
boost4S: Dr. Ulrich Eisele & Terje Noevig · GLNS: Georg Lindner & Dr. Konrad Hildebrand
Disclaimer: The content of this page is provided for general informational purposes only and does not constitute legal, tax or other professional advice. It does not replace individual advice tailored to the specific circumstances of a case. No liability is assumed for the accuracy, completeness or timeliness of the information. Any decisions made on the basis of this page are at your own risk. For specific questions, please consult a qualified attorney, tax advisor or other professional.